
HOW AUSTRALIANS BECAME MUPPETS
 ANNOUNCEMENT: THERE WILL BE NO NECESSARY CHANGE
Australia once had the gumption to lead the world in matters of social reform.
Without obsequiously establishing whether it was being done overseas, Australia saw the need to introduce a federal land tax under the Fisher government in 1910.
It was abolished by the Menzies’ government in 1952.
Australian governments now check with the halls of power and privilege whether it’s OK or not for a tax measure to be introduced.
Kevin Rudd failed to do this in the case of the RSPT and lost his prime ministership over it.
Julia Gillard then consulted with the big boys before coming up with the MRRT which will capture tens of billions less of Australians’ common wealth to the public purse.
Australians have become completely beholden to the 0.1%.
Whether or not we like to admit it, we’ve become their muppets.
FORD TO SLASH 400 JOBS
HAVE YOU SEEN IT YET?

DON’T BE DUDDED ON HOUSING DATA
A top article by Philip Soos in “The Conversation” today:
BEWARE THE RENT-SEEKING ORGANISATION: DON’T BE DUDDED BY HOUSING DATA
One of the more interesting outcomes the 2011 Census produced was the figures concerning the housing market. The reason for this interest is how the results contrasted with the idea that Australia currently suffers from an acute housing undersupply or shortage. Taking the lead in promoting this idea is the National Housing Supply Council (NHSC), an organisation formed by the federal government in May 2008 to provide an in-depth analysis of the housing market. The NHSC is widely considered to be the peak body in this field.
Unsurprisingly, in its first report – State of Supply Report 2008 – released in March 2009, the NHSC concluded that a deficit or gap of 85,000 dwellings existed. Here was the most comprehensive study of Australia’s housing market, a dense 172 pages. The alarming shortfall of dwellings made instant headlines in the media, not least because it provided concrete proof that Australia’s rocketing housing prices were strongly affected by this shortage. Both government and industry broadcasted the NHSC’s results because it confirmed the suspicion that a shortage did, in fact, exist – and that something could now be done about it. The banking and real estate sectors were also very supportive, as their own arguments about a housing shortage were now considered irrefutable.
There was only one small problem: the purported shortage of 85,000 dwellings was complete fiction.
In order to arrive at the shortage, the NHSC had to employ a methodology of the most dubious nature – a travesty of basic science. The shortfall of 85,000 dwellings was composed of the following: 1) 9,000 to address homelessness of those sleeping rough, 2) 35,000 to address homelessness of those staying with friends and relatives, 3) 13,000 to house marginal residents of caravan parks, 4) 26,000 to increase the rental vacancy rate to three percent, and 5) an extra 2,000 to round up to the nearest 5,000!
The problems with this analysis are legion, and were quickly unmasked by Australian economists Kris Sayce and Steve Keen, and are covered briefly here. While homelessness is indeed a serious problem with tens of thousands suffering from this plight, these persons (typically on the lower income scales) do not have the financial power to turn their needs into demand on the property market. Instead, the NHSC produced evidence of social need but not actual demand. The same goes for the residents of caravan parks.
The fourth category is an interesting one because it assumes that data sourced from the Real Estate Institute of Australia (REIA) and its state-level affiliates are also based upon sound methodology. As I have covered elsewhere, the reported vacancy rates are likely to be severely biased downwards given the appalling methodology, data-gathering techniques, and lack of independent oversight (auditing). The last point is self-explanatory: who on earth rounds up to the nearest 5,000?
These highly questionable statistics were produced by Australia’s “peak” body. The NHSC is a body stacked with industry and former government professionals. Its continued funding would most likely quickly dry up were they to find that no shortage existed. If instead a surplus was found, the NHSC’s brief existence would come to an end as dwelling supply considerations are found not to be an issue in price inflation.
The outcome is obvious: if a shortage can be found, then government is much more likely to enact policies favourable to industry. Asking the NHSC if there is a shortage is similar to asking Dracula if the blood bank needs to be expanded because of a deficit – the answer is already predetermined and reflexive.
Little more could be expected in the 2010 and 2011 reports. The NHSC performed a backflip, admitting that it was uncomfortable with its previous methodology given the obvious problems with it. It is unlikely that the NHSC would have changed course if not for the barrage of ridicule it experienced from those who read the report and were honest enough not to give their silent approval. Each report provided an increasingly dismal prognosis as the shortage had increased to 185,000 in 2011 and, if present circumstances remained the same, there is expected to be a shortage of 640,000 dwellings by 2030.
But nothing changed. The NHSC had to find another pretext for the pre-supposed shortage, this time by creating a category called “underlying demand”, driven primarily by immigration and other demographic factors. This would appear to be a more sound methodology if not for the fact that the numbers were simply made up again.
The pseudo-science of the NHSC has not prevented vested interests from promoting its conclusions as fact and crucially relies upon the public not reading through hundreds of pages (630 in all) of economic and statistical analysis to understand this. After all, the public is supposed to trust the “experts”. It is worth reading through these three reports in order to realise how the phrase“lies, damned lies, and statistics” rings true.
The non-existent housing shortage probably comprises the most popular argument used by the bubble deniers to justify astronomical housing prices. As Australia is apparently suffering from a chronic deficit of dwellings, demand is greatly outstripping supply, leading to rising prices.
The problem with this argument is it can’t explain why prices started to rise in 1996 and have skyrocketed onwards, especially during 2001-2004. Annual population growth between 1996 and 2005 registered at approximately 1%, but dwelling growth (adjusted for demolitions and discontinuations) was greater over this period. In fact, 2007 was the first time since 1950 that population growth was higher than dwelling growth. If the housing shortage argument was correct, housing prices should’ve started to rise from 2007 onwards, not 1996.
The shortage argument, however, is not new. Every country that has suffered through a housing boom followed by a crash (a bubble) in recent years have always had its so-called ‘experts’ claim that prices were based upon fundamental valuations due to dwelling shortages.
Take the US as a case study. Leading institutions such as the Federal Reserve, National Association of Realtors, California Building Industry Association and Harvard University’s Joint Center for Housing Studies produced sophisticated studies to show that the $8 trillion housing boom was caused, in part, by dwelling shortages. These studies were authored by professors, PhDs, and businesspeople, all with extensive knowledge and experience but with conflicts of interest that could fill a small book. Yet, their expertise was as illusory as the shortage when the housing market crashed. The same again occurred in Ireland and Spain to the point where these three countries are now bulldozing entire neighborhoods to reduce some of the massive oversupply.
Going back to point first made in the introduction, the 2011 Census revealed Australia had 7.8 million households, 900,000 lower than the NHSC’s figure, with population also growing by 300,000 less than previously estimated. These figures have come as such a shock that the NHSC chairman has reported that an undersupply could be incorrect. In fact, Morgan Stanley researchers have found that the current 228,000 dwelling undersupply has now become an oversupply of 341,000, a huge turnaround.
Given the flawed nature of the NHSC’s reports, the run-up in housing prices is likely due to other factors, specifically the escalation in mortgage debt used to finance real estate speculation. As of 2011, mortgage debt reached $1.2 trillion or 85% of GDP. Combined with personal debt, this climbs to $1.3 trillion or 95% of GDP, a staggering sum. Also of concern is the $53 billion in subsidies and tax breaks that property owners receive.
Perhaps the NHSC can stop wasting our taxpayer dollars and instead investigate these leads.
IT’S AS EASY AS THIS

WOODY’S 100

I was readin’
Leviticus twenty-five
… came across
verse twenty-three:
“The land shall not be
sold forever,
this land belongs to you and Me.”
Not unlike his own verse:-
As I was walkin’
I saw a sign there
and the sign said ‘Private Property’,
but on the other side
it didn’t say nothin’,
that side was made for you and me!
LONGWAVE MEMORIES
“LongWave Basics
by Bryan Kavanagh
22 December 1999 11:20 UTC
>At 06:06 AM 12/21/99 -0700, Tom Drake wrote:
>
>> I wrote
>> 1) Demographics – no.
>> 2) Collective memory – no.
>> 3) Master clock – no.
>> 4) Rent-seeking as a result of taxes – yes.
>>
>> If 4 remains obscure, then 1, 2, & 3 will forever remain as candidates.
>> When we are able humbly to acknowledge that we are indeed
>> inextricably fused with air, and are every bit as reliant
>> upon other natural resources, we will begin to gain some insight into
>> the utter economic absurdity, the devastating wastage of human potential
>> of taxing wealth-creation. If ever we do lift this veil, then the
>> naturalness of a community charge on the use of natural resources for
>> necessary public service and infrastructure will hit us in a blinding
>> flash. Then and only then, will the Longwaves list be redundant.
>>
>> – Bryan Kavanagh
>>
>————————————————————————–
>Bryan,
>
>I have read your site and followed your posts for over three years.
>Your work on real estate cycles has been very interesting to me
>and has helped my own understanding of the Long Wave.
>
>But I do not understand *HOW* the “economic absurdity…. of
>taxing wealth creation” rather than taxing the “use of natural
>resources” is a cause of the LongWave itself.
>
>Could you go into this in greater detail, and since this is a more
>Long Wave-related discussion than what goes on at the site itself
>in the past year, perhaps it should go there?
>
>Regards,
>
>Tom Drake
>
>Tenorio Research
>editor@TenorioResearch.itgo.com
OK, Tom. On the assumption that people here on the Longwaves list may be interested, I’ll attempt the task.
DEMOGRAPHICS: Our neo-Malthusian friends would have it that population increase leads to shortages. What, then, of the benefits of specialisation and mass production? At what point exactly do benefits attaching to these commence to reverse upon themselves? IMO, of itself, demographics has little or no influence on the K-wave.
COLLECTIVE MEMORY may seem appealing, too, but what are we really saying here? What *is* it precisely that becomes obscure to the collective memory? Excessive debt? Financial collapse? Recession? Depression? Really?
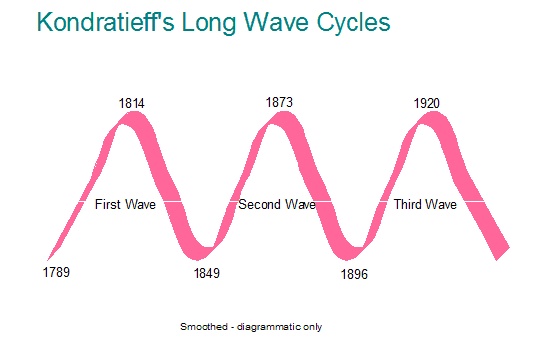
The MASTER CLOCK theory will also have its adherents, especially on a list such as the Kondratieff Wave.
But none of these theories describes the economic fundamentals of what *causes* the economy to derail.
The birds continue to eke out a chirpy living; so the question becomes what are *we* doing wrong?
Clearly, the problem is the extraordinary knot which repetitively develops in our distributional system.
Do we not we hear much about the community decrying the paradoxically widening gap between the rich and the poor in this ‘healthy, booming economy’? What is the process by which this gap widens – because, eventually, if Joe Sixpack no longer has a dollar in his pocket and can’t service his debts: the wheels of the economy must start to fall off.
The wealthy cannot make the economy go round by themselves – they need Joe. They won’t admit it, but he is integral. Many on the Longwaves list hold this process began to unfold in the early seventies. I believe its pace quickened discernibly in 1990/’91, after the collapse of western commercial real estate markets in 1989, and the process will gradually roll from denouement to conclusion.
[Segue] Why do people *have* to work for others? What if people all had the opportunity to work for themselves? Under the latter scenario, owners of capital would have to bid up wages in order to attract workers away from their own pursuits. This would never do: so those who run the show have to think up a ruse to keep people in their place. A new form of slavery, perhaps?
This was no better exemplified than in the case of the founding of the colony at South Australia. Wages and living conditions are notoriously better in a new colony, such as also the US once was. However, a not-too-nice chap by the name of Edward Gibbon Wakefield, who wrote a book called “England and America”, thought his class still needed cheap labour in these circumstances. Although his family was well off, he had abducted two heiresses and spent time in jail for kidnapping the third with intent to marry. He had been doing some thinking whilst interned in Newgate prison.
Wakefield thought there was a way by which you could found a colony which was not based upon cheap *convict* labour, as Sydney town had been. Why not simply release land to the colonists “at sufficient price” that only the wealthy will be able to afford their ‘town block’ and rural broadacre parcel – so others will have to work for years before they are able to afford a deposit, much less pay it off. [Enter the mortgage, ‘the grip of death’.]
There’s your cheap, subdued (cowed?) labour force.
Wakefield touted his theory, ‘The Wakefield Plan’, for colonising South Australia, New Zealand & Canada. The wealthy lapped it up. The Church also thought it had great merit. It would stop people from seeking to raise themselves beyond their proper station in life.
[Segue again: to a pier in Auckland, New Zealand, 1890.] Two men, one the tough former explorer Sir George Grey, governor of New Zealand, and former governor of the colony of South Australia, where he had seen Wakefield’s plan break out into a depression as the investors’ land bubble burst. Wakefield’s ideas were in opposition to Grey’s duty to society and compassion for working people . The other man: an American by the name Henry George. They shook hands, meeting only briefly, because George’s ship was quickly bound for Australia.
I fancy the discussion went something like this:
“That fellow Wakefield is now in New Zealand with his Plan, I see, Sir George.”
“Yes, Henry. He’s a friend to the rich, and a bane to all others!”
“Deucedly using my P – R = W + I to advantage the already-privileged, too!”
“Just so, Henry: just so. He has always been one with an eye for the main chance at society’s expense.”
[Cutting to the chase]
As times recover after the depression, and people get back to work, it is often not only employment that begins to grow again. Land price also gets up off the floor where it needed to remain. As land prices are permitted to resurrect with prosperity, so do mortgage commitments; so does the taxation of labour and capital.
Taxes cascade throughout the economy into every nook and cranny, doubling the prices of goods and services – as distinct from a community charge on resource rents which cannot be passed on in costs and prices.
The twin pathologies—-taxes and land prices—-pick up … mortgages growing, growing….until massive debt and speculative rent-seeking by the wealthy (and those who aspire to be like them) starts to choke off real wealth production….. once again.
Another depression.
Innovation; demographics; collective memory; master clock? Nah. Taxes, land prices, debt and rent-seeking, rotating in hopelessly repetitive cycles of boom and bust.
A community charge on land and other natural resource rents would break this cycle, IMHO.
A far better case is impeccably put at http://www.henrygeorge.org/chp1.htm
– Bryan Kavanagh“
INTRODUCING LAND VALUE TAXATION …

TOP STUFF FROM ALAN KOHLER
 A great piece from Alan Kohler in today’s Business Spectator.
Love some of those colorful lines, Alan!
Of course, I just had to comment. 😉
____________
Too fat to fail
Alan Kohler
Published 7:46 AM, 11 Jul 2012 Last update 7:46 AM, 11 Jul 2012
The problem with depressions, not that I’ve ever been awake during one before, is that you tend to get caught up in the minutiae of the moment – the gripping Libor-rigging scandal, the latest writhe in the agony of Europe, the latest twitch in the US economy.
We rush from scandal to crisis clamouring for each to be punished or redeemed. But interesting as all this is, it distracts from the big picture, the real story, which is that the world has begun an epic, long-term balance sheet adjustment.
Because most western governments are insolvent, fiscal policy is dead. They maxed out their taxing power a long time ago and have been borrowing ever since. When it comes to the economy, governments are a spent force.
This has put central banks in charge, and they basically do one thing only: print money. If all you have is hammer, everything looks like a nail, so central banks naturally think the world’s problem is a lack of money, which they are busily solving.
The problem is a lack of money is not the problem, it’s solvency, and part of the reason for that is too much money, or rather too much credit.
Debt was built up through 30 years of current account imbalances after currencies were finally unshackled from the gold standard in 1971, and the depression of the 70s came to end in 1982.
Central banks, principally the Federal Reserve, complied in the process of debt build-up by holding down interest rates and allowing asset prices to rise, keeping balance sheets in the black.
The credit crisis of 2007-08 brought asset prices down rapidly and rendered banks suddenly insolvent, so they had to be recapitalised by governments. Now the governments of Europe, the US and Japan are insolvent and the only question is when the central banks will monetise their debt – that is, print more money and buy their debts.
Governments and banks, lashed together like cage fighters, have to shrink drastically to reflect the new reality of their balance sheets, but no one wants to shrink and they are fighting that like polecats at the same time as fighting each other.
Rigging Libor, the benchmark interest rate for most global lending, and which is bound to extend far beyond Barclays, was one way the banks attempted to avoid their fate.
As a result of the 30-year boom in their product (credit), banks became too big and, more importantly, came to believe their own bullshit. Bankers became so rich, they naturally felt this was due to their brilliance, so that when the magic stopped working in 2007 they felt no compunction in bending the rules. They were, after all, Masters of the Universe.
The financial industry must now shrink and learn humility. To use investment parlance, the world is overweight banking and it needs to return to the simple task of collecting savings and distributing them to those who require them.
Governments also grew too big and acquired too much self-belief as a result of easy debt. Budget deficits and current account deficits were easily financed by future generations and they are now asking for the money back.
As a result short-term government bailouts in Europe are getting shorter and shorter, and less worthwhile. Greece is in worse shape now than it was before being bailed out. Spain and Italy are heading down the same path.
The governments of Japan and the United States are both insolvent – that is, their debts are greater than they can service for long. There is no alternative than deflation, although they will probably try inflation first – that is, monetising the debt.
But the greatest danger for investors is to not recognise the deflationary forest because you’re too busy watching the trees.
That doesn’t necessarily mean not investing, although for some wary souls it does, but rather it means understanding that we’re in a long bear market that is now five years old and could have 10 years to run, as banks, governments and households go about shrinking their debts to better reflect their assets and income.
Bear markets like this cause heartbreak, but they also create wonderful opportunities.